
.svg)
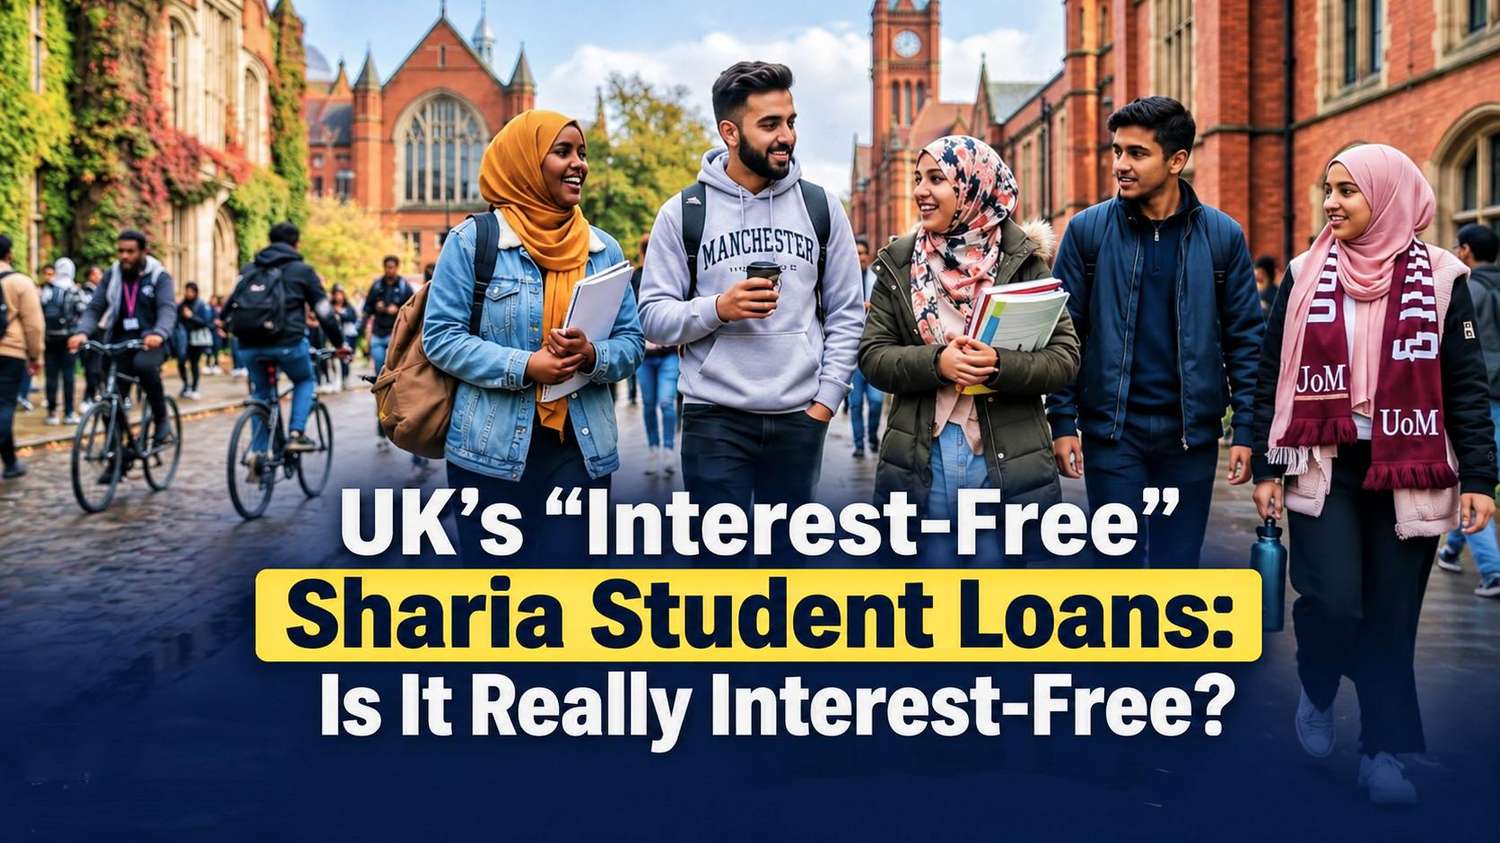
British universities have begun advertising “interest-free” sharia-compliant student loans to Muslim applicants, with the University of Bristol, the University of Leeds, University College London, City St George’s, Newcastle University and De Montfort University among those directing students towards the Alternative Student Finance (ASF) product. The scheme, developed by the Department for Education (DfE) with the Islamic Finance Council UK, is expected to become available as early as the 2026-27 academic year and is designed to allow students who cannot take on interest-bearing debt for religious reasons to access higher education. But the central question — whether the product is genuinely “interest-free” in any meaningful financial sense — is already generating fierce debate among economists, theologians and politicians. Daily Dazzling Dawn understands the Government paid the Islamic Finance Council UK more than £365,000 of public money to devise the scheme, and that taxpayers will remain liable for unpaid contributions, just as they are for conventional student loans.
The ASF product is built on the Islamic finance principle of Takaful, a form of group-based mutual support. Rather than borrowing a principal sum and accruing interest, students receive an “alternative payment” for tuition fees and living costs. After leaving university, they make income-based “contributions” into a shared fund that is ring-fenced exclusively to finance future students joining the same programme. The DfE has been explicit that the amounts and timings of these contributions will be identical to the repayments made by students on the mainstream loan system. “ASF will be introduced as soon as possible following the introduction of the Lifelong Learning Entitlement and will mirror the mainstream student finance offer, requiring the same repayments to the scheme as those required for conventional loans,” the Government stated in a written answer to the House of Lords on 7 October 2026. Any student eligible for student finance can apply, regardless of faith, and the product will be certified by an independent Islamic Finance Supervisory Board before launch. The DfE is also procuring a bank account that “must not bear or generate interest” to hold the funds, according to a Find a Tender notice published in April 2026.
The semantic distinction matters enormously. In a conventional loan, the extra sum paid above the principal is called interest, and it flows into the Treasury’s general pot. Under ASF, the extra sum paid above the principal is called a contribution, and it flows into a ring-fenced fund for future ASF students. The cash leaving a graduate’s bank account is the same in both cases — the same percentage of income, deducted at the same threshold, on the same dates. What differs is the label and the destination. Opponents argue this is a distinction without a financial difference, and that describing the product as “interest-free” risks misleading students into believing they will pay less overall. The DfE rejects that characterisation, insisting it would be “completely false to assert that Alternative Student Finance arrangements would give favourable treatment to Muslim students” and that “all graduates will be repaying their loans in full regardless of which system they use, including an equivalent alternative to interest”.
The political row has been sharp. Suella Braverman, the Reform spokesman for education, told journalists the scheme “creates a two-tier education system and divided society” and argued that “sharia loans are, by their very definition, exclusionary”. The Government’s decision to ring-fence ASF contributions rather than return them to the Treasury means that money repaid by sharia-loan graduates will never contribute to general public spending — a structural difference from the mainstream system that critics say entrenches a parallel financial architecture. Supporters counter that the ring-fencing is precisely what makes the product Islamically legitimate: the contributions fund a mutual support pool, not a state revenue stream. Daily Dazzling Dawn learned that official forecasts already estimate almost half of all student debt will never be repaid, meaning the taxpayer absorbs the shortfall under both systems. The risk profile, in other words, is identical.
The theological argument has an economic dimension. An Islamic thinktank, Equi, published a report on 21 October 2026 estimating that some 6,000 students a year forgo university because of concerns about interest-bearing debt, and that enrolling them could generate a £450 million economic premium per cohort. Mary Hunter, director of research at Equi, told Times Higher Education that “across the board…the interest-based system doesn’t seem to be working for young people”. The report also called for universities to provide proportionate faith-based space on campus and for the Office for Students to introduce minimum standards for religious provision. Equi’s polling of more than 1,300 students found that 52 per cent feel faith is important to them, yet only 24 per cent believe their institution does its best to attract candidates from religious groups. The ASF debate, in other words, is not merely about loan mechanics; it is about whether higher education is structured to include or exclude communities whose ethical frameworks differ from the default financial model.
The prohibition at the heart of the debate is unambiguous in Islamic scripture. The Qur’an declares in Surah Al-Baqarah (2:275): “Those who consume interest will stand on Judgment Day like those driven to madness by Satan’s touch. That is because they say, ‘Trade is just like interest’ — but Allah has permitted trade and forbidden interest”. The same chapter issues a direct command in 2:278: “O you who believe, fear Allah and give up what remains of interest, if you are true believers”. And 2:279 warns: “If you do not, then be warned of war from Allah and His Messenger. And if you repent, then you have your principal, wronging not and not being wronged”. The scriptural text forbids riba — any guaranteed increment on a loan of money — and demands that the lender recover only the principal. Whether the ASF contribution, which is calculated as a percentage of income and may in total exceed the principal, falls foul of that prohibition is a question the Government’s supervisory board will have to answer definitively. Some Islamic scholars have already argued that the existing student loan system is permissible because its repayments function more like a graduate tax than a traditional debt; the British Board of Scholars and Imams has sought to reassure Muslims on that point. The ASF scheme implicitly rejects that reasoning by treating the mainstream system as religiously problematic for a significant portion of the Muslim community.
The deeper issue is not whether the word “interest” appears on a statement. It is whether a graduate who pays tens of thousands of pounds above their principal — into a mutual fund rather than a Treasury account — has avoided riba in substance or only in nomenclature. The Government’s answer is that the Takaful structure, certified by scholars, satisfies Islamic law. The critics’ answer is that a contribution by another name still costs the same. Until the supervisory board publishes its reasoning and the first cohort graduates, the “interest-free” label will remain a claim in search of a verdict.

.jpg)